Division 7A: can a director just take money out of the company account?
A common misconception is that the cash sitting in your company's bank account belongs to you personally. It doesn't. The Australian Taxation Office uses Division 7A of the Income Tax Assessment Act 1936 to stop directors and shareholders dressing up dividends as loans. Get it wrong, and the entire withdrawal becomes a deemed unfranked dividend — taxed at the director's marginal rate with no franking credits to soften the blow.
Division 7A: can a director just take money out of the company account?
A common misconception is that the cash sitting in your company's bank account belongs to you personally. It doesn't. The Australian Taxation Office uses Division 7A of the Income Tax Assessment Act 1936 to stop directors and shareholders dressing up dividends as loans. Get it wrong, and the entire withdrawal becomes a deemed unfranked dividend — taxed at the director's marginal rate with no franking credits to soften the blow.
What is Division 7A and why does it exist?
Division 7A applies to private companies and treats certain payments, loans and debt forgiveness to shareholders (or their associates) as deemed dividends. The point is to stop business owners building up retained earnings in a company taxed at 25%, then quietly withdrawing the cash without paying personal tax on it. If the amount you take isn't formal salary, a properly franked dividend or a complying Div 7A loan, the ATO will treat it as a deemed dividend.
"Our partners bring together the right expertise and the right relationships to deliver real results for your business, your family and your future."
Why directors fall into the Division 7A trap
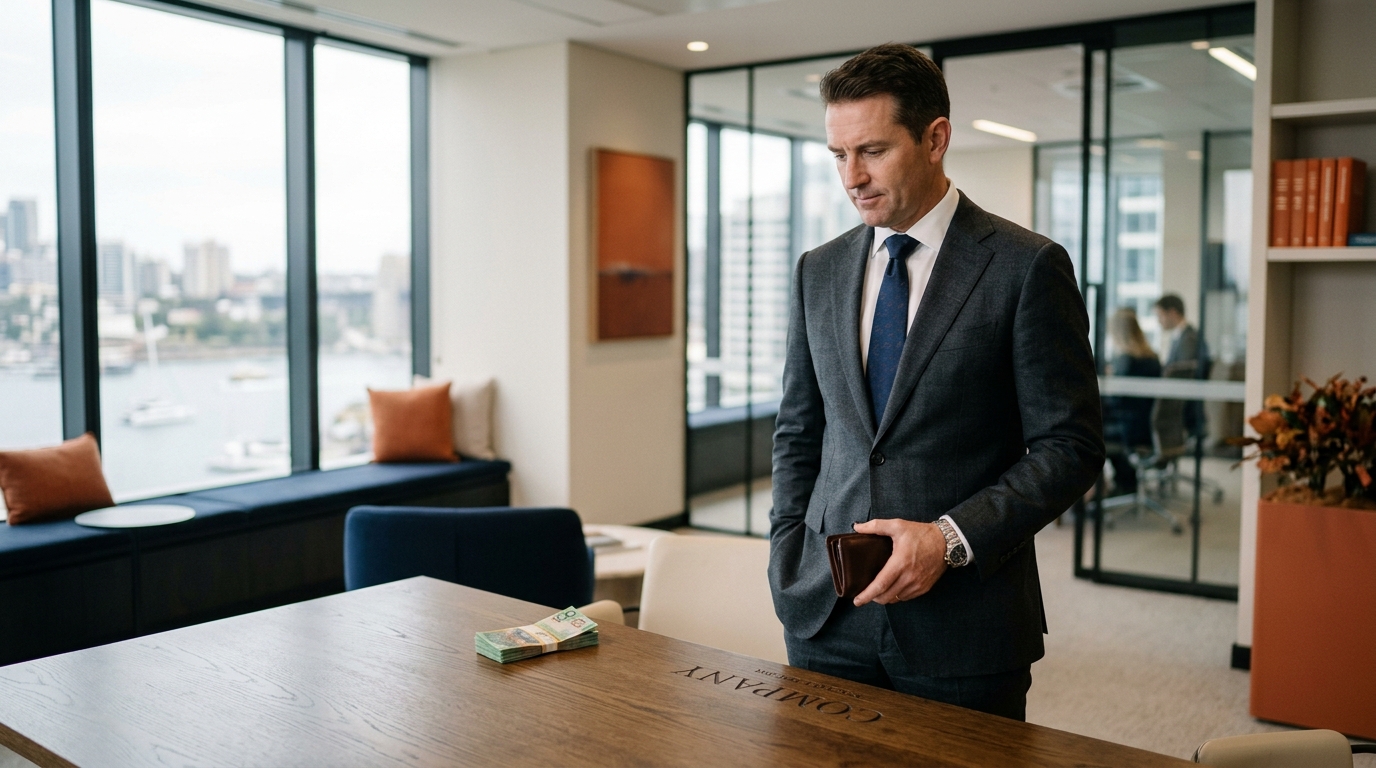
Most cases aren't deliberate tax evasion — they're paperwork failures. A director takes $30,000 from the company to renovate a kitchen, intends to repay it, doesn't sign a written loan agreement, doesn't make the minimum yearly repayment, and the ATO treats the whole $30,000 as a deemed dividend in that year. Marginal tax at 47% means $14,100 in tax that was easily avoidable.
How we help you make it happen.
From compliance to optimisation — pick a topic to explore how we work with you.
1. Salary or director's fees
Run through payroll, PAYG withheld, super paid. Deductible to the company, fully taxed in the director's hands. The cleanest method.
2. Franked dividends
Paid out of retained earnings after company tax. Director receives a franking credit equal to the company tax already paid — preventing double taxation.
3. A complying Division 7A loan
Written agreement, ATO benchmark interest rate (8.77% for 2025–26), minimum yearly repayments over 7 years (unsecured) or 25 years (secured against real property).