Business Structure in Australia: Sole Trader, Partnership, Company or Trust?
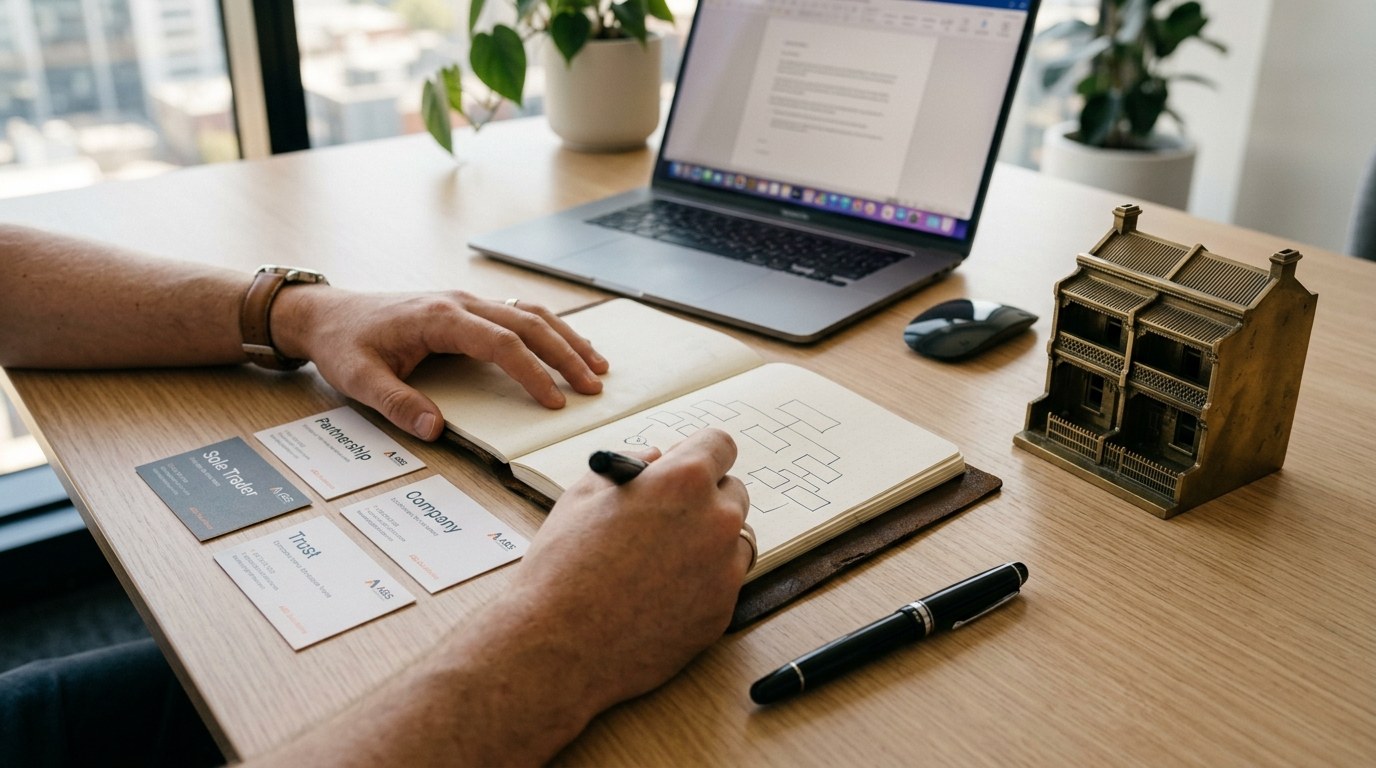
One of the first big decisions any new business owner in Australia has to make is what legal structure to trade under: Sole Trader, Partnership, Company (Pty Ltd), or Trust. It looks like a simple tick-box on an ABN application, but it actually shapes how much tax you pay every year, how exposed your personal assets are, and how easily you can raise capital or sell the business later. Get it wrong, and you could end up paying more tax than necessary — or worse, putting your house and savings on the line when the business hits trouble.
Business Structure in Australia: Sole Trader, Partnership, Company or Trust?
One of the first big decisions any new business owner in Australia has to make is what legal structure to trade under: Sole Trader, Partnership, Company (Pty Ltd), or Trust. It looks like a simple tick-box on an ABN application, but it actually shapes how much tax you pay every year, how exposed your personal assets are, and how easily you can raise capital or sell the business later. Get it wrong, and you could end up paying more tax than necessary — or worse, putting your house and savings on the line when the business hits trouble.
The four structures at a glance
In this guide, ABS Solutions (Registered Tax Agents and CPA Australia members) breaks down the four main structures in plain English — the tax treatment, the liability exposure, and which scenarios each one suits best. Choosing the right structure at the start is almost always cheaper than restructuring later, so it's worth understanding what each option actually gives you before you tick a box on the ABN form.
"Our partners bring together the right expertise and the right relationships to deliver real results for your business, your family and your future."
Business Structures in Australia Explained
A five-minute walkthrough of the four main business structures — sole trader, partnership, company and trust — from the ABS Solutions team.
1. Sole Trader: simple to start, but unlimited liability
A sole trader operates under their own name and Tax File Number (TFN) — there's no separate legal entity. This is the default starting point for most freelancers, consultants, delivery drivers, students running a side hustle, and small service businesses. Setup cost is close to zero: register an ABN and you're trading. Reporting is simple because business income flows into your personal tax return, and losses can generally be offset against your other personal income (subject to the non-commercial loss rules). The catch is unlimited liability — business debts are your personal debts, so if the business is sued or can't pay its creditors, your personal assets are exposed. You're also taxed at individual marginal rates: under the 2026–27 brackets, 30% on income between $45,001–$135,000, 37% on $135,001–$190,000, and 45% above $190,000. Best for: early-stage, lower-risk businesses — freelancing, consulting, e-commerce reselling, food delivery, and similar low-liability activities.
How we help you make it happen.
From compliance to optimisation — pick a topic to explore how we work with you.
A partnership is formed by two or more people (or entities) carrying on a business together — common among professional service firms (accounting, law, medical practices) and family-run trading or hospitality businesses. The partnership itself doesn't pay income tax, but it must still lodge an annual Partnership Tax Return; profits or losses are distributed according to the partnership agreement and included in each partner's individual tax return. Liability is unlimited and joint, meaning if one partner runs up debts or gets into legal trouble, the other partners can be held responsible too. Best for: trusted family members, friends or professional collaborators going into business together in a relatively lower-risk industry. We always recommend a written partnership agreement setting out capital contributions, profit shares, and exit terms before you start — it saves a lot of pain later.